Modernizing Public Financial Competency
The Financial Literacy and Education Commission (FLEC), alongside the US Department of the Treasury, has established an updated national framework designed to meet modern economic realities. Household financial decisions increasingly intersect with complex algorithmic interfaces, direct-to-consumer micro-saving apps, and rapid digital payment channels. The revised strategy shifts away from abstract budgetary theory and focuses on practical execution: establishing emergency reserves, understanding variable credit structures, and evaluating risk in digital financial environments.
Educational institutions and community organizations are being provided with standardized resources that bridge traditional accounting fundamentals with contemporary asset classes. By aligning federal agency efforts—from consumer protection bureaus to labor departments—the initiative aims to create cohesive financial readiness at key life milestones, including entering the workforce, managing first credit lines, and preparing for multi-decade retirement obligations.
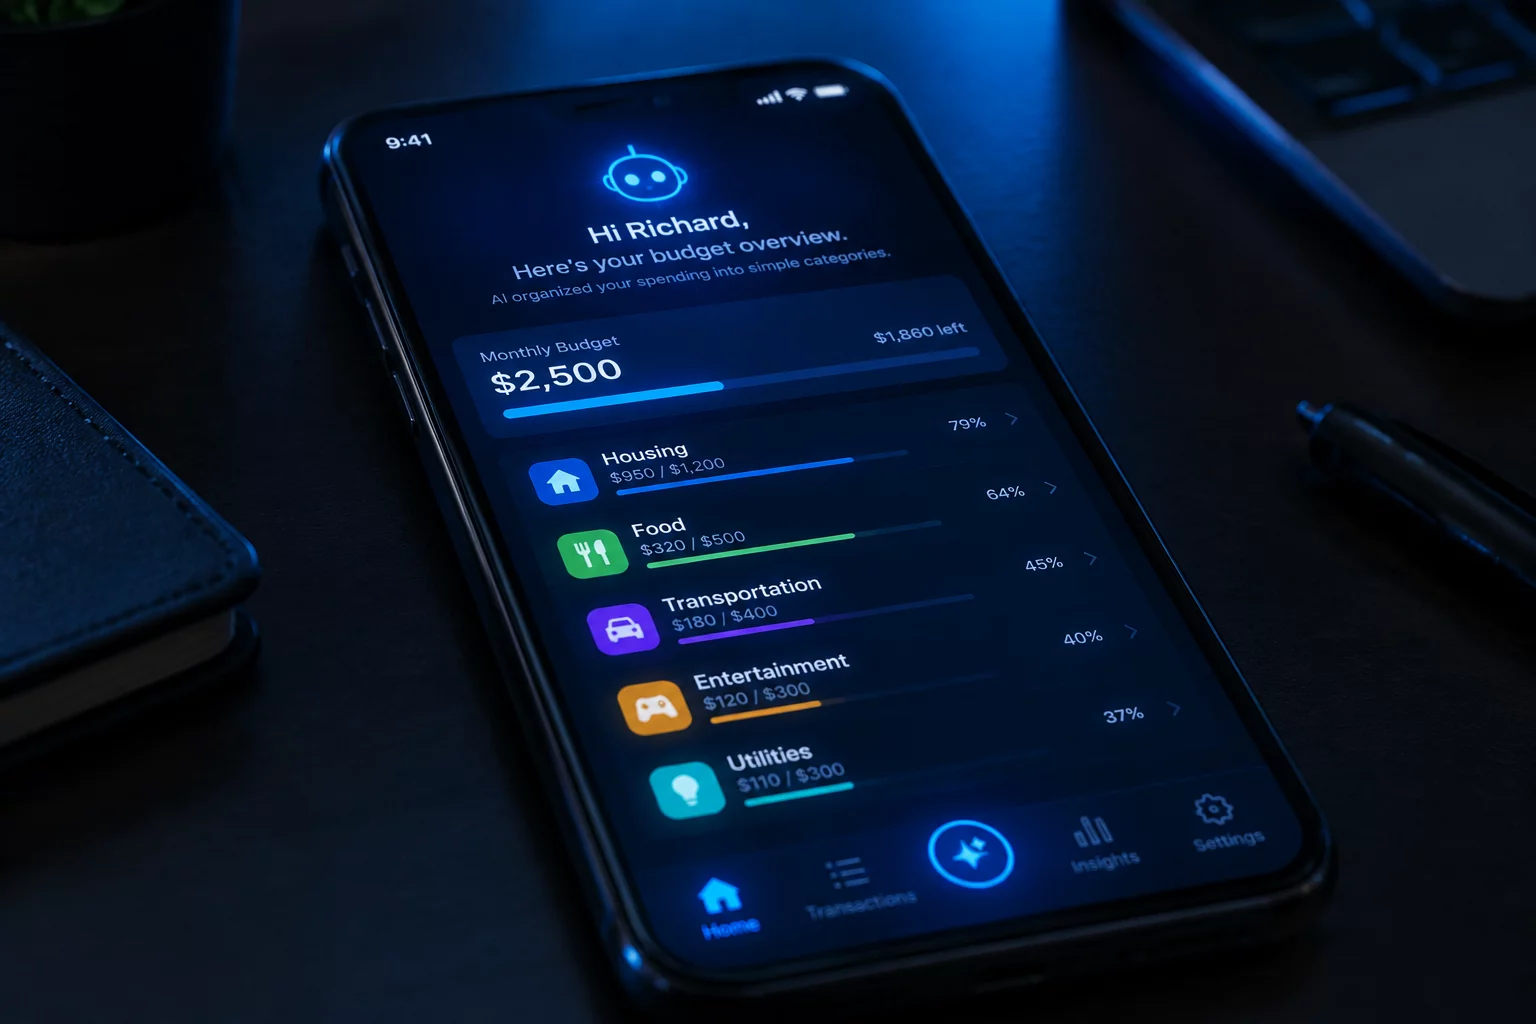
Track Your Capital Allocation With Precision
Utilize KU-BIRA's comprehensive dashboard to monitor asset distribution, portfolio metrics, and personal cash flow in one unified space.
Core Pillars of the Updated Framework
The strategic update centers around four foundational pillars designed to address long-term vulnerabilities in American household balance sheets. Regulatory bodies recognized that access to credit and capital markets has expanded significantly faster than consumer comprehension of risk, necessitating proactive intervention.
Effective financial education is no longer just about balancing checkbooks; it requires understanding digital risks, compound growth, and systemic asset security.
Implementation guidelines provide explicit pathways for integrating practical financial exercises into public school systems and corporate wellness initiatives:
- Early Capital Formation: Promoting early-life custodial saving, compounding literacy, and automatic micro-savings behaviors.
- Digital Literacy & Algorithm Awareness: Equipping consumers to evaluate gamified app features, predatory micro-loans, and high-interest installment debt.
- Fraud Defense & Identity Safeguards: Establishing direct educational counter-measures against widespread social engineering scams and synthetic identity theft.
Implications for Private Savers and Wealth Managers
For individual savers and institutional wealth managers, the updated national strategy highlights the growing expectation of transparent, verifiable financial data. As public literacy rises, demand shifts toward tools that aggregate fragmented holdings—including private equity, traditional equities, and digital assets—into coherent, risk-adjusted portfolio views.
Savers are encouraged to audit their own personal asset management setups, ensuring that diversified accounts are clearly monitored and that digital authentication mechanisms comply with top-tier cybersecurity standards. Structured tracking remains the essential foundation for turning literacy principles into resilient wealth preservation.