The Evolution from Manual Spreadsheets to Interactive Agents
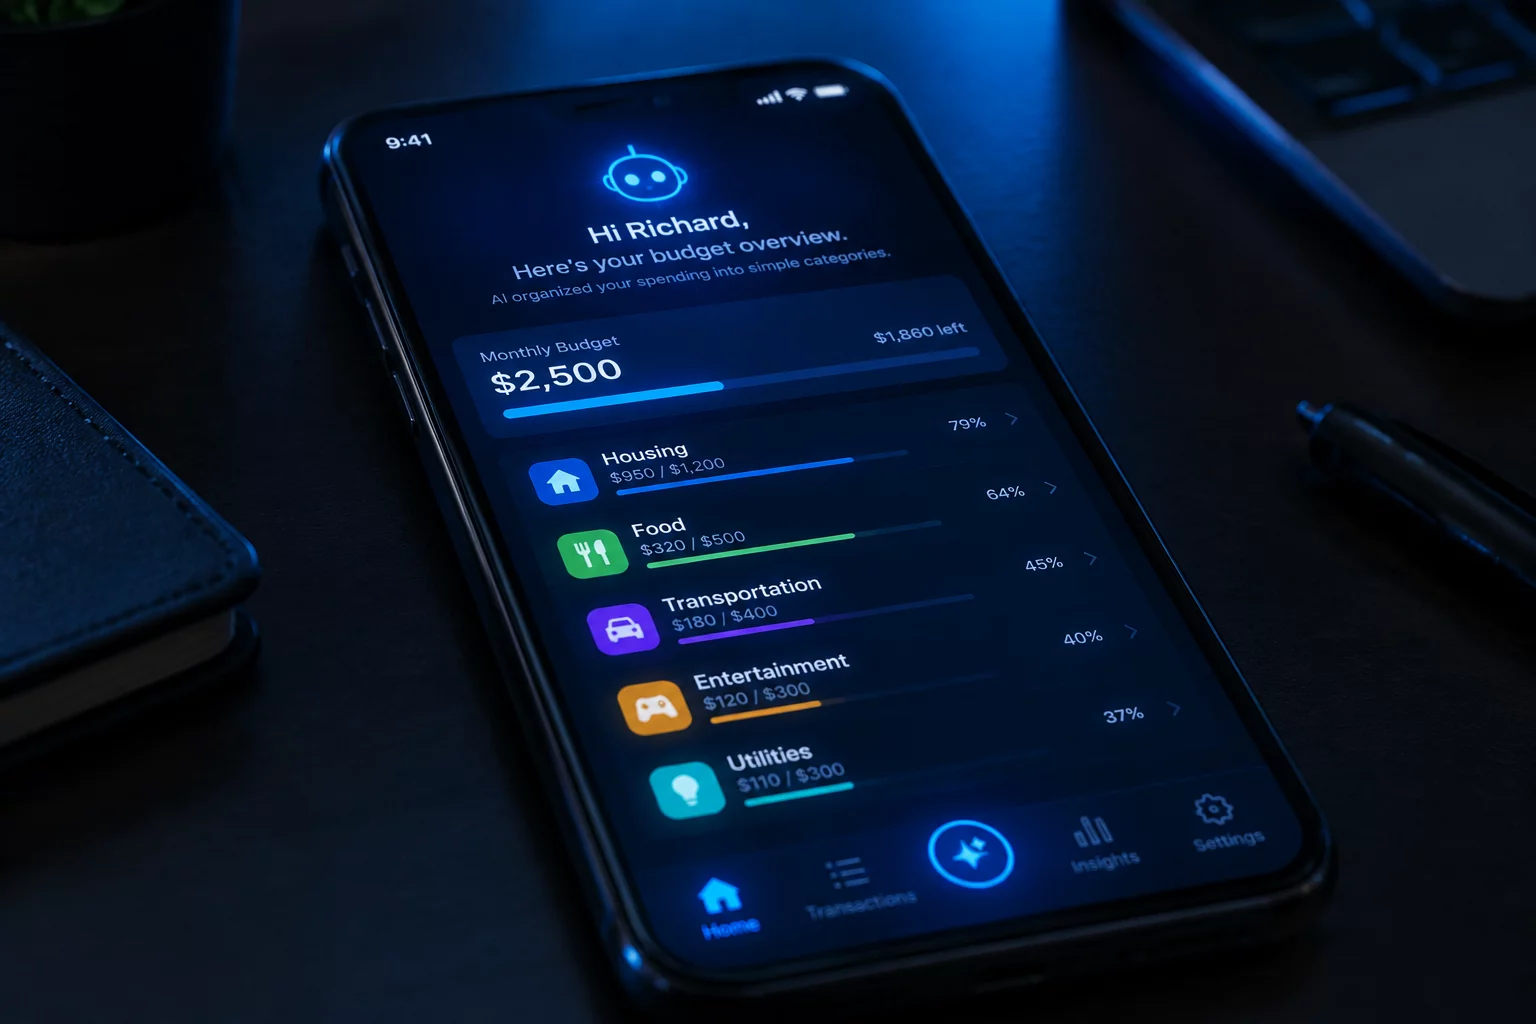
Personal financial planning long relied on fragmented spreadsheets, delayed statement reviews, and manual expense tagging. Recent enhancements to conversational artificial intelligence models have initiated a distinct behavioral shift across household finance. Consumers routinely present raw receipt data, credit card statements, and loan obligations directly to language models to identify spending anomalies and construct realistic cash reserves.
Following the deployment of specialized financial plugins and reasoning capabilities in widely adopted AI platforms, outgoing referral traffic directed toward dedicated budgeting platforms expanded significantly. Users discover that interactive prompts uncover discretionary spending leaks far faster than traditional static ledger applications.
Integrate AI Analytics With Your Assets
Connect multi-asset tracking, Carta integrations, and custom AI models inside a centralized financial command center.
Automated Debt Optimization and Transaction Classification
Managing high-interest revolving balances alongside fixed installment debt requires continuous mathematical optimization. Machine learning tools evaluate avalanche versus snowball debt payoff strategies in real time, calculating interest savings while factoring in unexpected cashflow variations. Instead of fixed formulas, dynamic simulations provide tailored repayment benchmarks adapted to each billing cycle.
Machine intelligence transforms passive financial records into proactive balance sheet guidance, reducing friction in daily financial decisions.
Modern financial aggregation architectures employ automated intelligence across several crucial functional layers:
- Context-aware merchant classification that resolves ambiguous digital purchase codes automatically.
- Predictive liquidity buffers that warn users of potential account drawdowns days before recurring bills settle.
- Custom scenario modeling that reflects interest rate adjustments across variable-rate debt obligations.
Data Security and Safe Protocol Architecture
Integrating artificial intelligence into personal accounting necessitates strict boundaries around sensitive credentials. Direct account access is avoided; instead, platforms deploy anonymized read-only connectors through established aggregators. This approach ensures that core credentials remain fully segregated from model inference environments.
With standards such as Model Context Protocol (MCP) gaining adoption, users can safely query their financial balances through their preferred intelligence tools while preserving total control over access permissions and data residency.