Macroeconomic Stabilization and Household Realignment
The latest macroeconomic indicators indicate a prolonged easing of severe price pressures across consumer sectors. With headline inflation settling near the 2.4% to 2.6% threshold, households are adapting their monthly financial routines to a predictable economic climate. Supply chain normalizations and balanced labor metrics have curtailed unexpected commodity cost spikes, allowing families to construct dependable forward projections for food, utility, and transportation expenditures.
This newly restored predictability encourages consumers to shift away from defensive stockpiling and short-term cash hoarding. Instead, financial planning methodologies now emphasize systematic capital distribution, balancing mandatory lifestyle costs with proactive balance sheet strengthening.
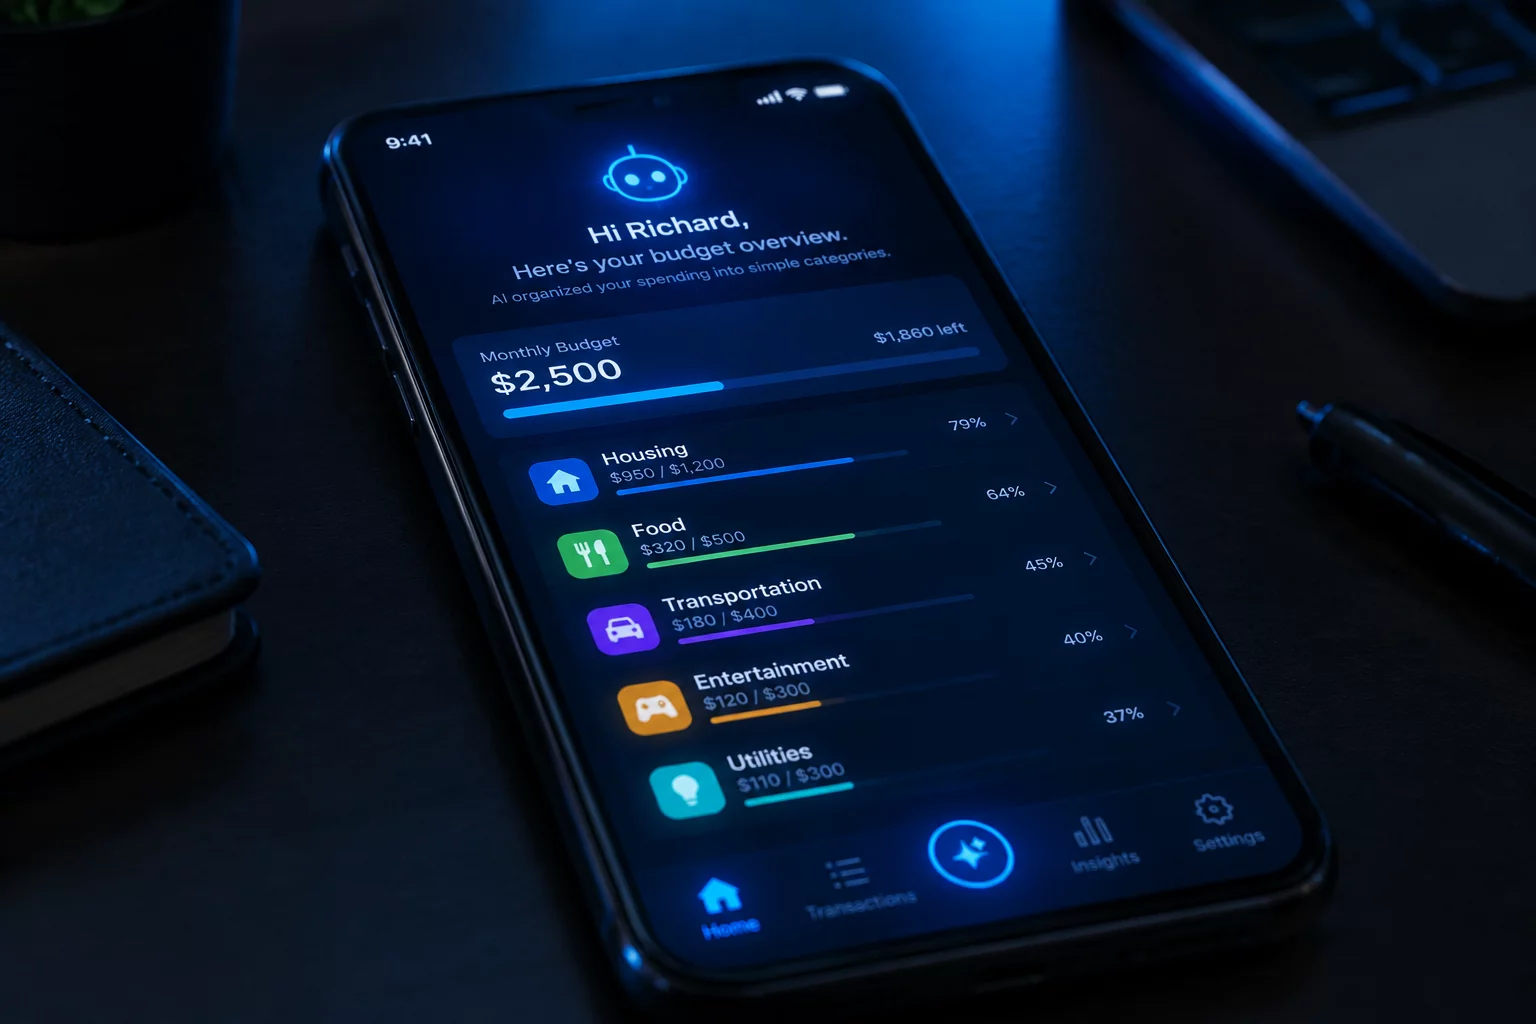
Organize Your Balance Sheet
Connect with our analytical tools to manage multi-account portfolios, track asset classes, and monitor liabilities.
Strategic Focus on High-Interest Debt Elimination
As price spikes diminish, attention has quickly pivoted toward addressing borrowing costs accumulated during prior high-rate cycles. Elevated interest rates on credit cards and variable loans continue to impose substantial drag on net wealth, prompting consumers to prioritize debt retirement over discretionary luxuries.
High-rate debt elimination remains the most reliable wealth preserver in an environment of stabilizing price indices.
Empirical data indicates that structured repayment models provide tangible balance sheet resilience. Key strategic patterns deployed by disciplined households include:
- Allocating unspent monthly margins toward revolving balances carrying interest rates in excess of 18%.
- Utilizing automated amortization schedules to reduce principal balances before redeploying surpluses.
- Maintaining liquid emergency reserves in yields above 4% to prevent emergency borrowing surges.
Long-Term Allocation Modeling and Liquidity Planning
With disinflation trajectories holding steady, capital allocation frameworks recommend maintaining an emergency cushion spanning four to six months of documented living expenses. This protective reserve buffers households against economic shocks while core surplus funds are allocated toward long-term equity growth vehicles and diversified asset pools.
Looking toward upcoming fiscal quarters, financial resilience will depend on disciplined execution. Households that effectively combine debt payoff with automated net worth tracking will achieve substantial structural stability regardless of broader macroeconomic fluctuations.